Recognition audit
Signals that this is the right method
- The problem states a force of interest δ or describes continuous compounding rather than a periodic effective rate.
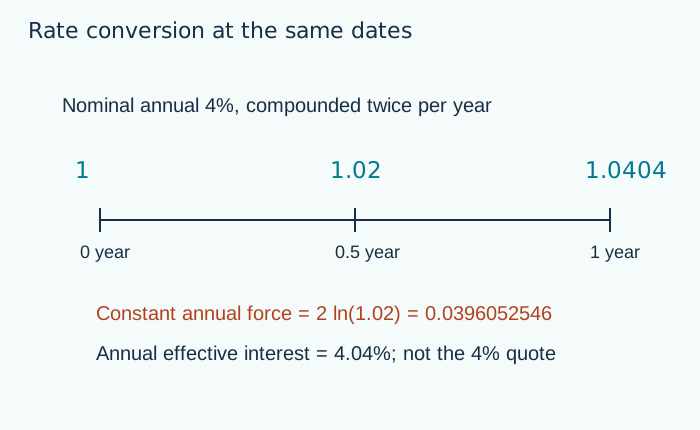
- An annual effective, nominal convertible, or discount rate must be converted before cash flows can be valued on one common basis.
- The force varies with time, so the accumulation factor must use an integral over the exact start and end times.
- Two investments use different rate conventions and must be compared through accumulation factors, not by comparing the printed percentages.